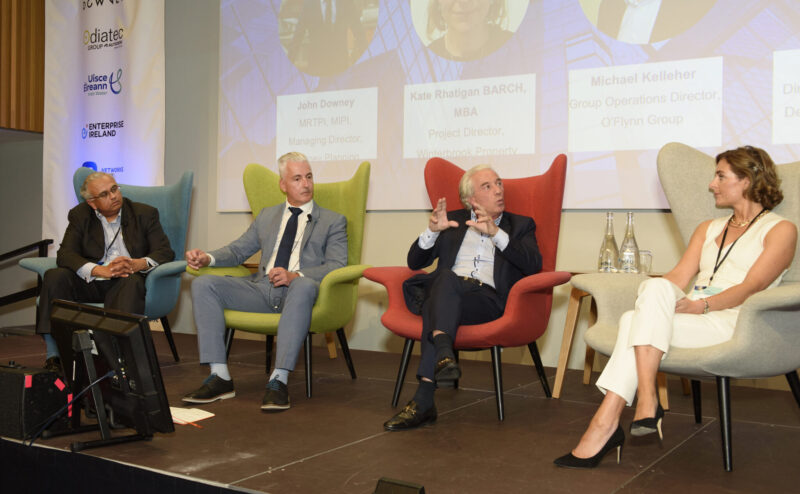
The Construction Industry Federation’s Annual Conference being held in Croke Park highlighted how maximising construction output under the National Development Plan over the next 10 years is essential to safeguard Ireland’s economic competitiveness, meet social needs, and deliver the infrastructure required for a resilient, productive future.
The Minister for Housing, Local Government and Heritage James Browne together with other senior Government members, industry CEOs, policymakers and statutory body representatives gathered at CIF’s flagship conference to address practical actions required to accelerate infrastructure and housing delivery across Ireland. The conference explored ways to tackle Ireland’s infrastructure delivery bottlenecks and accelerate capital projects across energy, water, transport, and residential development.
Coinciding with the conference, the CIF released its Quarter 3 2026 Construction Outlook Survey, revealing persistent domestic constraints in public works procurement alongside strong international export growth.
Addressing delegates at the Conference ─ themed ‘Ready to deliver: Ireland’s decade of construction’, CEO of the Construction Industry Federation Andrew Brownlee said: “Ireland faces a critical ten-year window before demographic pressures begin to constrain fiscal capacity. The country is entering a defining decade for construction where plans and ambition must translate into relentless delivery. Our quarter three 2026 survey findings show strong export growth across data centres, pharma, and transport. However, four in ten firms are carrying out no public sector work due to low margins, price-based tendering, and administrative burdens. We need greater certainty around project pipelines, faster progress through the system and stronger coordination across Government, industry and the wider infrastructure ecosystem.”
Q3 Construction Outlook Key Findings
The CIF’s Quarter 3 (Q3) 2026 Construction Outlook Survey published today (23.09.26) shows that construction activity remained resilient in quarter two 2026, supported by strong growth in exports. According to the survey, cost pressures have eased from earlier in the year but continue to weigh on margins.
Based on responses from 159 construction companies, the survey shows turnover, new orders and employment all recording stable to modest growth, with more firms expecting increases than decreases across every key indicator for Q3.
Export activity was particularly strong, with 67% of exporting firms reporting a year-on-year increase in turnover in Q2, driven by data centres, pharmaceutical facilities, and roads and transport projects, and 57% expecting further growth in Q3.
Cost inflation has moderated compared with earlier quarters, with fewer firms reporting increases in raw material, labour and pricing costs than at the start of the year, although a majority still expect further rises. Public works participation remains limited, with 40% of firms expecting to carry out no public sector work in Q3, and low margins and administrative burden cited as the main barriers to greater involvement.
Commenting on the Q3 findings, Andrew Brownlee said: “Out latest research among the sector points to an industry that continues to perform well, with export activity in particular delivering some of the strongest results we have recorded. Cost pressures have eased since the start of the year, which is welcome, but they remain high enough to affect margins on projects across every sector.
“The area that requires most attention is public works. Four in ten firms are carrying out no public sector work at all, and the reasons given, low margins, price-based tendering and administrative burden, are within Government’s ability to address.”
Key Survey Findings
Exporting Construction Services
Business Turnover
New Orders
Costs and Pricing
Employment
Public Works
Andrew Brownlee said: “The construction sector enters Q3 2026 with positive momentum, supported by strong export performance and cost inflation that, while still elevated, has moderated from earlier in the year. The clearest constraint on the industry’s capacity to deliver is public works participation, with four in ten firms carrying out no public sector work at all. CIF is calling for reform of public procurement to broaden participation and support the pace of housing and infrastructure delivery.”
Read the Q3 2026 CIF Construction Outlook Survey.